Most housing and commercial schemes offer some version of the same choice: pay more upfront and less over time, or spread the cost across a longer, smaller-instalment plan. Neither is universally 'better' — it depends on your cash flow and how you value certainty.
A larger downpayment usually reduces your total monthly commitment and can sometimes unlock a better overall price. It suits buyers with savings on hand who'd rather close out the obligation sooner.
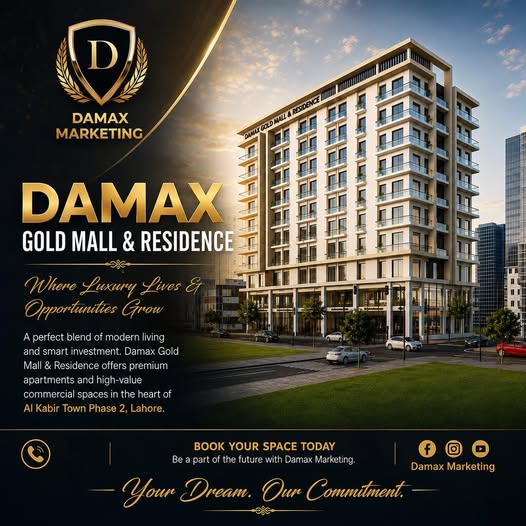
A longer instalment plan — like the flexible plans available on Damax Tower and Damax Gold Mall & Residence — keeps monthly outflows predictable and manageable alongside your regular income, letting you plan around salary or business cash flow instead of a large lump sum.
Whichever you choose, ask for the full schedule in writing, confirm what's due at each stage, and make sure the plan's total adds up to the price you were quoted before you commit. Our team can talk you through both options for any current Damax listing.